Reconstructing a former captain’s accounts, preparing two prior-year returns and organizing financial statements for the mortgage process.
What the 2013 Allegro Ventures maritime employment dispute reveals about yacht captain classification, payroll responsibilities, employment contracts, and the financial risks of treating crew as independent contractors.
Managing yacht crew payroll requires more than paying salaries on time. From crew changes and employment arrangements to payroll taxes, funding and reporting, a structured process helps owners and captains maintain control, reduce administrative errors and keep vessel operations running smoothly.
Florida mortgage rates remain high, and that changes the math for buyers and rental property owners. The key question is not just where rates may go next, but whether a property still works on today’s financing terms.
The IRS says eligible taxpayers affected by ongoing events in Israel may have certain return and payment deadlines postponed to Sept. 30, 2027.
The Federal Reserve’s October 2. 2026 enforcement action with Ontario Bancorporation matters to business owners because banking compliance issues can add friction to business financing.
An inherited property may arrive with a familiar low tax bill, but your federal tax basis usually changes and state property tax treatment may not follow the same logic. That gap can affect holding costs, sale planning, and cash flow almost immediately.
Recent yacht tax changes affect ownership cost, financing assumptions, and state tax exposure. Here is what has changed and what to review before relying on deductions.
The SEC is seeking comment on whether the CFA designation should qualify individuals for accredited investor status.
The delay in most rental-property tax returns is usually not the tax form itself. It is missing support: acquisition records, income detail, expense backup, and prior-year depreciation information that determines whether Schedule E is accurate.
FinCEN has withdrawn a proposed rule targeting certain digital-asset transactions, removing one potential compliance layer. For businesses with crypto exposure, the key is knowing what is now off the table—and which existing anti-money-laundering rules still apply.
A new Tax Court decision filed on September 21, 2026 adds another reminder that LLC tax treatment is not just a formation choice; it is an operating reality the IRS will measure against its own rules.
The IRS has reminded homeowners to review available tax benefits, but the practical value of those benefits in 2026 still depends on how the return is prepared, especially whether itemizing produces a real tax benefit. For homeowners and real estate investors, the key question is not just what deductions exist under IRS guidance, but which home-related deductions are actually usable, supportable, and worth planning around.
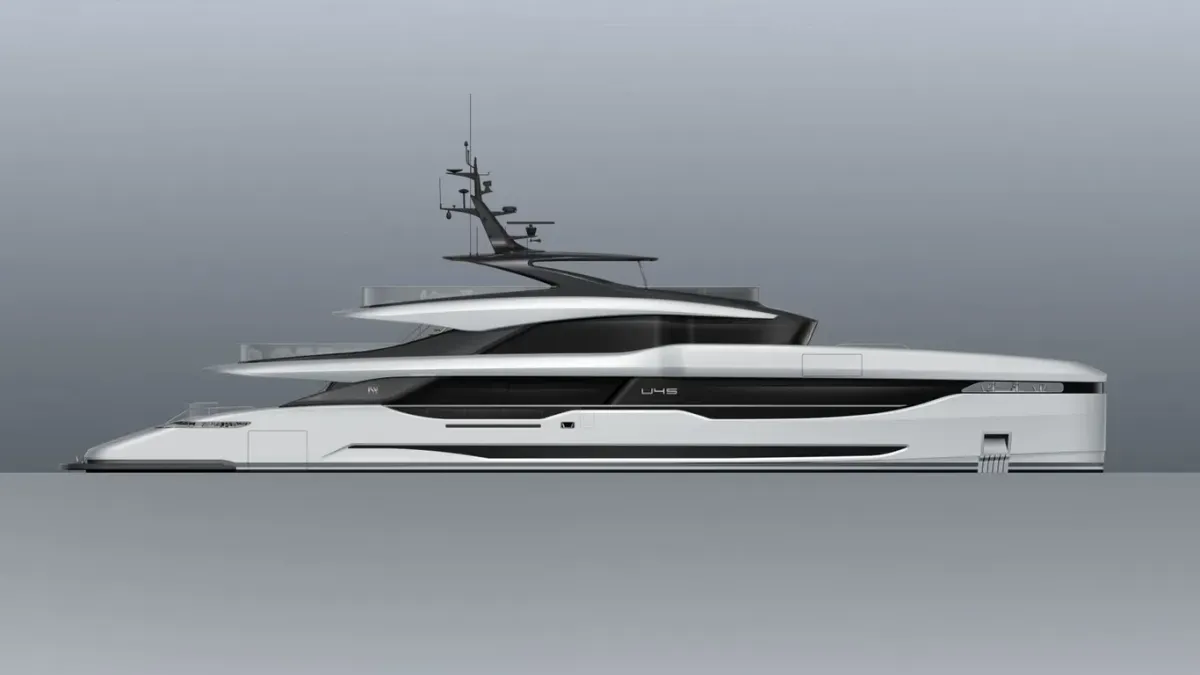
A new 138-foot hybrid superyacht highlights the shift in vessel design. For owners and operators, the bigger question is how purchase structure, operating use, and documentation affect the vessel’s true cost.
A September 22, 2026 Tax Court memorandum decision in *Toscano Holdings, LLC, Toscano Investments, LLC.
Physicians with hospital wages and separate locum tenens or moonlighting income often discover that strong W-2 withholding does not fully cover taxes on their side work. The main planning issue is not just what you owe, but when you need to pay it, what you can deduct, and how to keep the two income streams coordinated.
Florida Amendment 3 is being discussed as a tax-cut measure, but the practical issue for property owners is not a headline savings claim by itself. For homeowners and investors, the more useful question is whether any reduction in one tax line is later offset by other costs, shifted obligations, or pressure on local funding. Because the proposal remains under discussion rather than finalized, it is best used as a planning scenario, not a booked savings assumption.
The IRS has formally eliminated 71 pieces of outdated Internal Revenue Bulletin guidance, a housekeeping move intended to improve clarity and reduce reliance on material the agency no longer considers necessary. For affluent households and closely held businesses, the practical issue is not the announcement itself but whether any older positions, memos, or compliance workflows still point to guidance that has now been withdrawn.
The IRS has updated the planning documents that often foreshadow exempt-organization guidance. For private foundations and charitable structures, this is an early compliance signal, not yet a rule change.
Real estate investors can still use Delaware Statutory Trust structures in like-kind exchange planning, but the more immediate planning issue is timing: current IRS Opportunity Zone relief remains defined by prior federal guidance, while bonus depreciation strategy depends on asset timing and facts, not broad assumptions. The practical question is which parts of your gain deferral and depreciation plan are actually supported by current authority.
Banks are expanding AI use quickly while regulators focus on governance, oversight, and model risk. That can affect how your company is reviewed and served.
Texas has issued current guidance confirming that its franchise tax treatment of depreciation is being updated to follow federal law more closely, including the effect of the OBBBA on bonus depreciation. For real estate investors using Texas entities, the immediate issue is not headline tax reform—it is whether prior margin assumptions, cost recovery timing, and report calculations still hold.
In South Florida, financing cost can change the economics of a deal more quickly than a modest move in price. Here is how MFS thinks investors should frame that tradeoff.
The Treasury Department and IRS have announced steps aimed at preventing private schools that engage in racial discrimination from qualifying for or keeping…
Revolut founder Nik Storonsky denies owing Cecil Wright & Partners €17.5M over the reported €350M purchase of Lürssen superyacht Nixie.
How owner personal use affects charter economics, documentation and tax analysis for a yacht operated as a charter business.
H.R. 10153 could create FEIE relief for qualifying U.S. merchant mariners, but it is only proposed legislation and most yacht crew likely do not qualify.
Yacht charter accounting must track gross revenue, commissions, APA, crew, owner funding, personal use, OPEX, CAPEX, refits, reconciliations and tax-basis records.
A $10 million yacht can require $14.66M in first-year liquidity and $2.49M per year to operate. See crew, fuel, dockage, charter, refit and resale costs.
Where a $100,000 yacht charter fee actually goes after commissions, APA, crew, operating costs and owner economics.
A $25 million yacht can require $4.76M a year and nearly $397K a month to fund. See crew, fuel, dockage, insurance, charter offset and five-year cost.
Illustrative first-year and annual operating costs for a $5 million yacht, including crew, dockage, insurance, maintenance and reserves.
A $50 million purchase can require $62.4M in year-one cash, $8.7M of annual owner funding and more than $110M before resale over five years.
Can charter income make a yacht pay for itself? See the real math for $5M, $10M and $25M yachts, including APA, commissions, owner use and break-even weeks.
Compare 2026 yacht ownership costs across $1M–$50M yachts: crew, fuel, insurance, dockage, maintenance, repairs and refit reserves by vessel size.
See what yacht owners actually keep after commissions, charter costs and annual OPEX—with 6, 10, 14 and 18-week profit and ROI scenarios.
Can $1 million in yacht charter revenue become owner profit? See what remains after commissions, operating costs, APA treatment and financing.
A $500,000 salary is high income—but taxes, housing, childcare and lifestyle commitments can leave surprisingly little investable cash. Here is how to turn income into lasting wealth.
The federal estate-tax exemption is $15 million in 2026. IRS rules show why families far below that amount can still face major tax and inheritance issues.
BRABUS yachts can cost from approximately $148,000 to more than $1.4 million before tax. See every Shadow model’s price, fuel use, financing payment, Florida tax, VAT exposure and estimated five-year ownership cost.
Use the 2026 wealth-building stack to prioritize emergency cash, debt, 401(k), HSA, IRA, real estate, brokerage accounts and business capital.
The 2026 yacht market has fewer pre-owned sales but higher average values, more listings and more price reductions. Learn what buyers should examine before purchasing.
Are yacht crew meals deductible in 2026? Learn how Section 274(o) affects crew provisioning, charter guests, APA expenses and luxury yachts.
The Fed held rates in July 2026, but mortgage rates can still move. Learn what yacht crew, self-employed buyers, and refinance candidates should do now with documentation, rate locks, and affordability planning.
See the 12 monthly financial reports every yacht owner should receive, from budgets and cash forecasts to payroll, APA, refits and tax-ready records.
A prominent attorney’s tax evasion and mortgage fraud sentence shows why tax returns, business records, foreign accounts, IRS debt, and mortgage applications must tell the same financial story.
IRS automatic penalty relief begins in 2026. See who qualifies, which penalties AEP covers, how it replaces First-Time Abatement, and what remains due
Eight North Carolina tax preparers pleaded guilty in a pandemic-relief tax fraud scheme involving false paid sick and family leave credits. Learn what the case means for taxpayers, business owners and tax professionals.
Treasury is screening federal payments against death records. Learn how this may affect deceased taxpayer refunds, surviving spouses, estates, executors, business owners, Form 1310, Form 56, Form 1041, and post-death payment delays.
Compare the best online mortgage lenders in 2026 with a broker-guided strategy before applying. This guide uses Forbes Advisor’s lender list as a starting point, then explains how borrowers can compare Rocket Mortgage, PNC Bank, New American Funding, Rate, Mr. Cooper, Ally, and live mortgage options through Loan Factory
The IRS Working Families Tax Cuts hub brings new deductions, Schedule 1-A guidance, withholding tools, family tax updates, business provisions, and scam warnings into one place. MFS helps taxpayers interpret the rules and prepare a cleaner filing plan.
Explore 2026’s trending yacht clubs from a Yacht Owner’s perspective, including top U.S. clubs, guest access, transient dockage, reciprocity, event calendars, cruising value, etiquette, membership considerations, and practical arrival details for planning a smarter yacht season across the U.S. coasts.
Yacht management companies operate the vessel. Yacht accountants independently verify the financial results. Learn why yacht owners need both for clearer reporting, stronger controls, tax-ready records, charter profitability, payroll coordination, and owner-side financial oversight.
Florida protected series companies are now available as of July 1, 2026. This guide explains how Florida LLC owners can use protected series for asset separation, lower filing costs, tax planning, payroll records, and stronger financial administration.
Yacht crew salary guide for 2026–2027 with pay ranges for captains, deckhands, stewardesses, engineers, chefs and officers by yacht size, plus tips and rotation.
Learn how to start a yacht charter business in 2026, including charter economics, owner use, LLCs, maritime compliance, accounting, depreciation records and tax documentation.
Working on a foreign-flagged yacht does not automatically qualify income for the FEIE. Eligibility depends on tax home, foreign-country presence, travel days, itinerary and employment arrangement.